A budget built around one forecast can look reassuringly precise until a major customer pays late or a supplier raises prices. Financial scenario planning for business replaces that single expectation with several plausible operating outcomes. Instead of asking, “What will happen?”, it asks, “What would we do if conditions changed?”
The aim is not to predict every surprise. It is to understand how sales, costs and payment timing affect profit and available cash, then decide which actions make sense before pressure builds.
Start with the decisions, not the spreadsheet
Scenario planning becomes useful when it informs a choice: whether to hire, take on a lease, buy equipment or build a cash reserve. Identify that decision first. A retailer considering a second location needs different assumptions from a consultancy deciding whether to recruit two employees.
Choose a planning horizon that reflects the commitment. Monthly projections over 12 months suit many operating budgets, while a weekly cash view may be necessary when money is tight. Keep the model small enough that someone can explain its workings without searching through dozens of tabs.
Build a credible base case
Your base case should represent a reasonable current expectation, not an ambition disguised as a forecast. Start with recent financial results, confirmed orders, recurring customers and known obligations. Separate the factors you can influence from the factors you cannot.
Useful drivers include sales volume, average selling price, customer retention, gross margin, payroll, rent, supplier costs and the delay between invoicing and receiving payment. In financial modeling, make those drivers editable inputs rather than typing a new profit figure for each outcome.
For a simple business forecast, estimate revenue as customers multiplied by average revenue per customer. Subtract the variable costs associated with delivering that revenue, followed by fixed operating costs. Create a separate cash forecast because an invoice recorded as revenue does not necessarily become cash that month. For more detail, a cash flow forecasting guide can help distinguish earnings from actual receipts.
Build three connected business forecast scenarios
Best case: growth with realistic constraints
In the best case, demand strengthens or customer retention improves. But greater sales may require more stock, contractor hours or working capital. Model the extra costs and cash demands alongside higher revenue. A scenario that assumes sales climb without any delivery costs increasing is usually wishful thinking.
Base case: conditions broadly follow expectations
The base case acts as the comparison point for budgets and performance reviews. It should incorporate known seasonality, expected expenses and typical customer payment patterns. Do not automatically assume every month grows at the same rate.
Worst case: a plausible downside, not an apocalypse
Choose a specific setback, such as losing a substantial client, a prolonged sales slowdown or slower collections combined with rising supplier prices. Some costs will fall with sales, but rent and core salaries may not. Model the timing of any savings carefully; cutting a contract may require notice or incur charges.
These cases should be internally consistent. If your downside assumes fewer customers, adjust associated product costs and collection patterns too. Keep a short written explanation of every changed assumption so the numbers remain understandable.
A worked example: when cash tells a different story
Consider an illustrative service business with monthly revenue of $50,000, variable delivery costs of 30% and fixed operating costs of $25,000. Its base-case operating profit is $10,000 before interest and tax.
In a best case, revenue reaches $60,000 with the same cost percentages and fixed expenses. Operating profit rises to $17,000. In a downside case, revenue slips to $35,000 and variable costs reach 32% of sales, while fixed expenses remain $25,000. The result is an operating loss of $1,200.
Now consider cash. Suppose the downside month starts with $40,000 in the bank, but only $20,000 of customer payments arrive because several invoices are delayed. If the business pays $11,200 in delivery costs and $25,000 in fixed expenses that month, ending cash is $23,800, assuming no other cash movements. The accounting loss is $1,200, yet the cash balance falls by $16,200.
That gap is why financial scenario planning must examine liquidity as well as profitability. A business can survive a modest paper loss yet struggle to meet payroll if receipts arrive too late.
Turn the downside into a contingency plan
A forecast alone does not protect the business. Attach actions to observable warning signs. For example, if expected cash falls below one month of essential outgoings, management might freeze discretionary spending, pursue overdue invoices and postpone nonessential equipment purchases. If the sales pipeline weakens for two consecutive months, recruitment plans could be reviewed.
Assign each action an owner and a lead time. Negotiating supplier payment terms may take weeks; cancelling a nonessential subscription may be immediate. Contingency planning works better when teams know what to do before a threshold is crossed.
Also test the actions themselves. Delaying stock purchases might conserve cash but cause missed sales. Reducing marketing might lower costs while further weakening demand. The strongest response protects the business without automatically damaging its recovery.
Stress-test assumptions and update the model
After comparing the three cases, change one driver at a time. What happens if customers pay 15 days later? How much sales volume can disappear before operating profit turns negative? How would a price increase affect demand? This sensitivity testing shows which assumptions matter most.
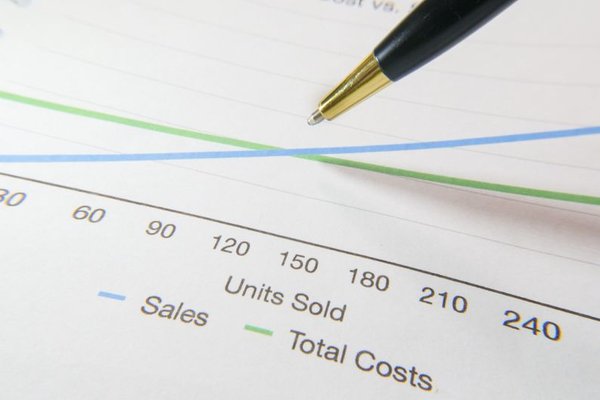
Compare actual results with the forecast each month, and update sooner after a material event such as losing a major contract. Record why expectations changed instead of quietly replacing old figures. Pair the model with a break-even analysis and a monthly business budget so your decisions remain connected to day-to-day operations.
A spreadsheet is often sufficient. Keep assumptions, calculations and results clearly separated, and check that beginning cash plus receipts minus payments equals ending cash in every scenario. More elaborate software is useful only if it improves accuracy or makes decisions easier.
Frequently asked questions
What is financial scenario planning for business?
It is the process of estimating how different combinations of operating conditions could affect revenue, expenses, profitability and cash flow. Businesses use the results to compare choices and prepare responses rather than rely on one forecast.
How is scenario planning different from forecasting?
A forecast estimates an expected outcome based on available information. Scenario planning explores several plausible outcomes under different assumptions. The two methods complement one another: the base forecast provides the starting point for alternative cases.
How often should business scenarios be reviewed?
Monthly reviews fit many businesses, with more frequent cash checks when liquidity is strained. Rework assumptions promptly after meaningful changes in demand, costs, financing or payment behaviour.
Do small businesses need sophisticated financial modeling software?
No. A well-structured spreadsheet can calculate revenue, costs and cash balances across a handful of scenarios. Reliable inputs, transparent formulas and clear action thresholds matter more than complex software.
Conclusion
The value of best, base and worst cases is not in finding the one that comes true. It is in discovering where your budget is vulnerable, how much cash a setback could consume and which decisions remain sensible across different conditions. Start with a few credible assumptions, revisit them regularly and use the findings to act earlier.