Two businesses can generate the same monthly sales and face very different financial risks. One has a costly lease and a small expense for each order. The other works from home but pays a contractor whenever a customer buys. The difference comes down to fixed vs variable costs in business, and it changes how each owner should budget, price services, and prepare for a slow month.
The useful question is not simply which costs are larger. It is how each expense behaves when activity changes. Once you understand that relationship, you can build a budget that responds to sales instead of relying on one optimistic forecast.
Fixed and Variable Costs: The Difference at a Glance
Fixed business costs generally stay unchanged as sales or production rise and fall within a particular period and level of activity. Rent, insurance premiums, and flat-rate software subscriptions are common examples. A shop normally owes its rent even when it makes no sales.
Variable expenses move with a measurable activity, such as items produced, orders shipped, or billable hours. Product materials, per-order packaging, and payment-processing charges often belong here. If a business produces twice as many identical units, its total direct material cost will usually rise too, assuming unchanged unit prices.
The distinction is about behavior, not whether a payment repeats. A monthly electricity bill may contain both a standing charge and usage-based charges. Likewise, a business may pay its staff fixed salaries while paying additional hourly workers when demand rises.
How the Two Categories Compare
Fixed costs are usually predictable in the short term but difficult to reduce quickly. Variable costs can rise sharply with sales yet tend to decrease when demand falls. Fixed cost per unit declines as more units share the same overhead; variable cost per unit may remain fairly steady until suppliers, processes, or prices change.
Some Operating Costs Don’t Fit Neatly into Either Box
Budgeting becomes more realistic when you recognise mixed and step costs rather than forcing every expense into two perfect columns.
A mixed cost contains a fixed base and a usage-based component. Imagine a delivery platform that charges $60 per month plus $1 per booking. Record $60 as fixed and $1 per booking as variable. Treating the entire bill as fixed would understate what happens when orders increase.
A step cost remains stable until the business crosses a capacity threshold. A bakery might need a second oven, larger premises, or another shift supervisor after production exceeds its current capacity. The new expense may then stay fixed across the next range of activity.
A Small-Business Example: What Sales Really Need to Cover
Consider a takeaway food business selling lunch bowls for $30 each. Its monthly fixed costs, including rent, insurance, and core staffing, total $2,400. Ingredients, disposable containers, and transaction charges add up to $12 per bowl.
Each bowl contributes $18 toward fixed costs and then profit: $30 selling price minus $12 variable cost. This $18 is the contribution margin per unit, not the final profit on the sale.
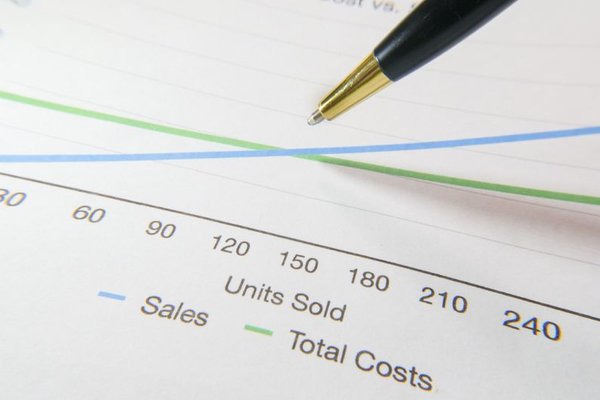
To find the break-even point, divide $2,400 in fixed costs by the $18 contribution per bowl. The result is 133.33, so the shop must sell at least 134 bowls to cover these modelled costs. The calculation assumes a constant price, constant variable cost per bowl, and sufficient capacity.
If it sells 200 bowls, revenue reaches $6,000. Variable costs are $2,400, leaving $3,600 in contribution. After $2,400 in fixed costs, the business has $1,200 in operating profit before any additional excluded costs or taxes.
Now suppose ingredient prices rise and variable cost reaches $15 per bowl. Contribution drops to $15 and break-even volume rises to 160 bowls. At 200 sales, modelled operating profit falls to $600. Revenue has not changed, but the business has lost half its profit cushion.
This is why a budget should track unit economics, not just total sales. A separate break-even analysis guide can help you test different price and cost combinations.
How to Budget for Both Cost Types
Start with the Costs You Must Cover
List recurring commitments for your chosen budget period, then flag contract renewal dates and potential step increases. Include costs that may be billed annually by setting aside the relevant share each month. A $1,200 annual insurance payment, for example, calls for roughly $100 of monthly planning provision, even though the cash payment happens once.
Next, estimate variable cost per unit or per order using actual invoices where possible. For service firms, the activity driver could be contractor hours per project rather than physical products. Keep a clear record of what each unit estimate includes.
Build More Than One Sales Scenario
Prepare a conservative, expected, and strong-sales forecast. For each scenario, calculate revenue, variable costs, contribution, and fixed costs separately. This shows how changes in sales affect your cost structure instead of hiding everything inside one percentage-of-revenue assumption.
Review the figures monthly. When materials rise faster than revenue, investigate supplier prices, waste, or product mix. If fixed expenses increase, ask whether the extra capacity will produce enough additional contribution to justify them. A simple monthly budget variance review often reveals problems earlier than a year-end profit statement.
What the Cost Mix Means for Pricing and Cash Flow
Pricing solely by adding a markup to direct materials can leave a business unable to cover its overhead. Calculate the contribution each sale generates, then judge whether realistic sales volume will cover fixed commitments. A useful next read is a product pricing strategy guide that compares contribution margin with markup.
Cash flow adds a second layer. A profitable month can still create a shortage if customers pay late while rent, payroll, or supplier bills come due earlier. Build a cash flow forecast showing when money actually arrives and leaves. Keep reserves for fixed commitments during slower periods, and account for inventory purchases that may happen before the corresponding sales.
Frequently Asked Questions
Is payroll a fixed or variable cost?
It depends on the arrangement. A guaranteed monthly salary may be fixed within the planning period, while hourly labour that changes with workload may be variable. Overtime and commission can create mixed payroll costs.
Are utilities fixed costs?
Often they are mixed. A basic service charge may be fixed, while electricity, water, or other usage charges vary. Separate those components when the amounts are significant.
Can fixed costs change over time?
Yes. Fixed means unchanged within a defined activity range and time period, not permanently unchanged. Rent renewals, new equipment, and expanded staffing can all raise future fixed costs.
Which costs should a small business cut first?
Look at contribution, service quality, and cash commitments before deciding. Removing wasteful variable spending helps every sale; reducing unnecessary fixed commitments can lower the sales needed to break even. Protect spending that supports profitable demand.
Conclusion
Fixed and variable costs tell two different stories about business risk. Fixed commitments establish the baseline you must cover; variable costs determine how much each additional sale contributes. By separating them, testing realistic sales scenarios, and matching the budget to payment timing, you can make better pricing, hiring, and cash decisions without mistaking busy periods for sustainable profit.